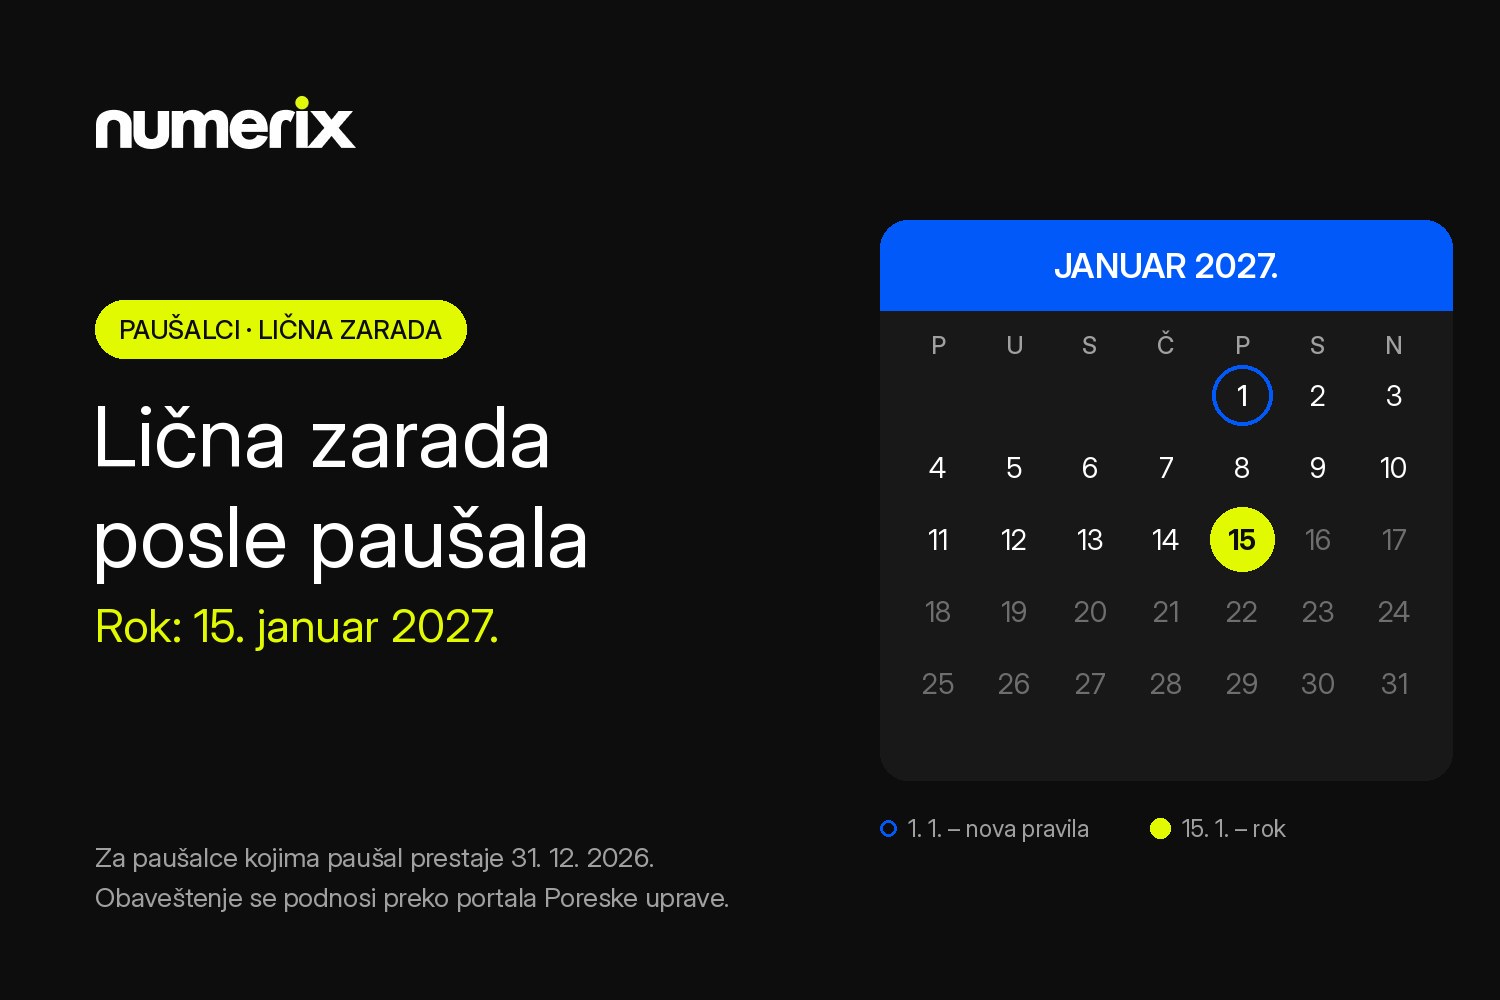

On 6 October 2026 the Ministry of Finance (Ministarstvo finansija) issued opinion no. 4319558 2026 10520 004 000 011 001, which answers a question that troubles many paušalci (flat-rate taxed entrepreneurs) at the end of the year: by when must you opt for a personal salary (lična zarada) if your flat-rate status ends on 31 December 2026? The answer: by 15 January 2027 at the latest.
What has changed
Amendments to the Personal Income Tax Law (Zakon o porezu na dohodak građana, "Official Gazette of RS", no. 80/2026) changed Article 33a. From 1 January 2027, a flat-rate entrepreneur who loses the right to flat-rate taxation and must switch to keeping business books (Article 42, paragraphs 5 and 6) can opt to pay themselves a personal salary. The notification is submitted electronically, through the Tax Administration (Poreska uprava) portal, within 15 days of the date the right to flat-rate taxation ends (Article 33a, paragraph 6).
For other entrepreneurs the old deadline applies: the choice is submitted by 15 December of the current year, for the period from 1 January of the following year.
What the opinion says
The Ministry considers that a paušalac whose right ends on 31 December 2026 "may submit, through the Tax Administration portal, a notification of their choice to pay a personal salary starting for 2027, no later than 15 January 2027."
Reasoning: the amended Article 33a applies from 1 January 2027, so the 15-day period is counted from that day. The Ministry refers to Article 33a, paragraphs 1, 2, 3 and 6, Article 42, paragraphs 5 and 6, and Article 13, paragraph 3 of the Law. The opinion does not specify a form number – the notification is submitted through the Tax Administration portal.
Who it applies to
- Paušalci whose right to flat-rate taxation ends on 31 December 2026 (e.g. because they exceeded the 6 million dinar limit or entered the VAT system) and who keep business books from 2027.
- It does not apply to entrepreneurs who already keep books – for them the deadline is 15 December.
Example (illustrative)
Marko is a programmer and a paušalac. In 2026 he invoiced 6.4 million dinars, so from 1 January 2027 he switches to keeping books. He wonders whether he has to decide by 15 December, like entrepreneurs who already keep books. According to this opinion, he does not: if he submits the notification through the Tax Administration portal by 15 January 2027, from 2027 he can pay himself a personal salary instead of paying tax and social contributions through so-called self-assessment (samooporezivanje) – which in most cases is far less favourable.
Need help?
If you are switching from flat-rate taxation to keeping books, take a look at our bookkeeping services, and for the decision on a personal salary, get in touch through our tax consulting.
My advice
- If your flat-rate status ends on 31 December 2026, or you are even just close to the limit, be sure to contact your accountant and go through the options, legal obligations and deadlines together.
- Compare a personal salary with taxation of taxable profit for 2027 together with your accountant.
- Don't wait until the last day: submit the notification through the Tax Administration portal by 15 January 2027 at the latest.
- Keep the confirmation of submission.
- Arrange for your business books to be kept from 1 January 2027.
This article is for information purposes only and does not constitute a tax opinion for a specific case.
Sources: Ministry of Finance opinion no. 4319558 2026 10520 004 000 011 001 of 6 October 2026; Personal Income Tax Law, Articles 13, 33a and 42 (amendments, "Official Gazette of RS", no. 80/2026).